


A study released by the Bank for International Settlements on Oct. 13 links bank deposit repricing to a larger estimated slowdown in USDC growth than in USDT growth, so banks’ offers can shape stablecoin adoption differently for each issuer.
Higher deposit rates give holders a stronger financial reason to keep balances at a bank. In the study, a one-basis-point deposit-rate increase was associated with about 4.8% less cumulative USDC growth over ten weeks, compared with 1.9% less growth for USDT.
Researchers Rashad Ahmed and Iñaki Aldasoro used weekly data from January 2019 through June 2025. The BIS published the October edition after a first version appeared on March 24, and the earlier abstract already reported the stronger USDC response.
Exchanges can offer variable rewards to eligible customers, adding another price to the competition for balances. That makes the historical issuer split useful for adoption forecasts while leaving today’s bank-versus-platform comparison to be established.

How the issuer estimates compare
The paper’s deposit-rate measure averages six national savings and money-market deposit-account series. It is distinct from the Federal Reserve’s policy rate and from the rate on any particular high-paying account.
The ten-week OLS point estimates separate the two issuers:
StablecoinEstimated change in cumulative log market-cap growth per 1 basis point of deposit repricingUSDC−4.8 percentage pointsUSDT−1.9 percentage points
Ordinary least squares (OLS) is the baseline statistical model, while the negative estimates describe slower growth relative to the model’s comparison path.
The authors interpret USDC’s larger response as consistent with its closer connections to US institutional and decentralized finance users. Those holders may have more reason to compare bank deposits with stablecoin balances, and they associate USDT’s weaker response with its offshore and developing-economy uses.
The data cannot identify which individual holders switched or which bank accounts were involved, so the issuer explanation is an interpretation of the pattern.
For adoption forecasts, the implication is that a deposit-rate assumption applied to all stablecoins can conceal different competitive pressures. The point estimates suggest a stronger US deposit-pricing relationship for USDC in this sample, without establishing a fixed response for either token in every market environment.
For stablecoins in aggregate, the baseline ten-week estimate is about 2.8% less cumulative growth per basis point of deposit repricing. A second model, using an instrumental-variable approach intended to isolate deposit repricing, produces a larger estimate of about 9.1% less growth.
That approach exploits banks’ stronger pass-through of policy-rate changes when the federal-funds target midpoint four weeks earlier was at least 3.125%. It depends on the resulting variation affecting stablecoin demand through deposit repricing after the other controls.
The controls cover policy and Treasury rates, Bitcoin prices, the dollar index, and market volatility, helping distinguish deposit-price competition from broader investment conditions, without proving the identification assumption.
The authors flag instrument weakness: the first-stage F-statistic is 9.78, below the conventional threshold of 10 they cite. With only one high-rate episode in the sample, the larger estimate has limited evidence to support its application to a different rate cycle.
In the paper’s instrumental-variable charts, USDC’s ten-week 95% confidence band remains below zero, while USDT’s includes zero.
A separate deposit-tier comparison also supports the direction of the relationship, using differences in how banks reprice preferred money-market and savings accounts.
Checks for the Silicon Valley Bank episode, crypto events, trading volume, and DeFi yields retain negative relationships. Responses among balances supplied to lending protocols remain imprecise. The evidence supports competition, but its magnitude depends on the model and sample.
Rewards change what holders compare
The return on a stablecoin balance is also shaped by the platform on which it sits. In research published June 19, the BIS distinguished two economic models for exchange payments to stablecoin holders.
Under reserve-based remuneration, an exchange transmits part of the income generated by the issuer’s reserve assets to holders. Under activity-based remuneration, payments are tied to lending, trading, and other market activity.
The bulletin uses Coinbase and Binance as respective examples, while acknowledging that the boundaries are imperfect.
In its historical exchange-yield evidence, Coinbase’s USDC holding yield followed policy and reserve yields more closely, while Binance’s yields were more exposed to crypto activity. These are different ways to fund returns on balances, with different reasons those returns change.
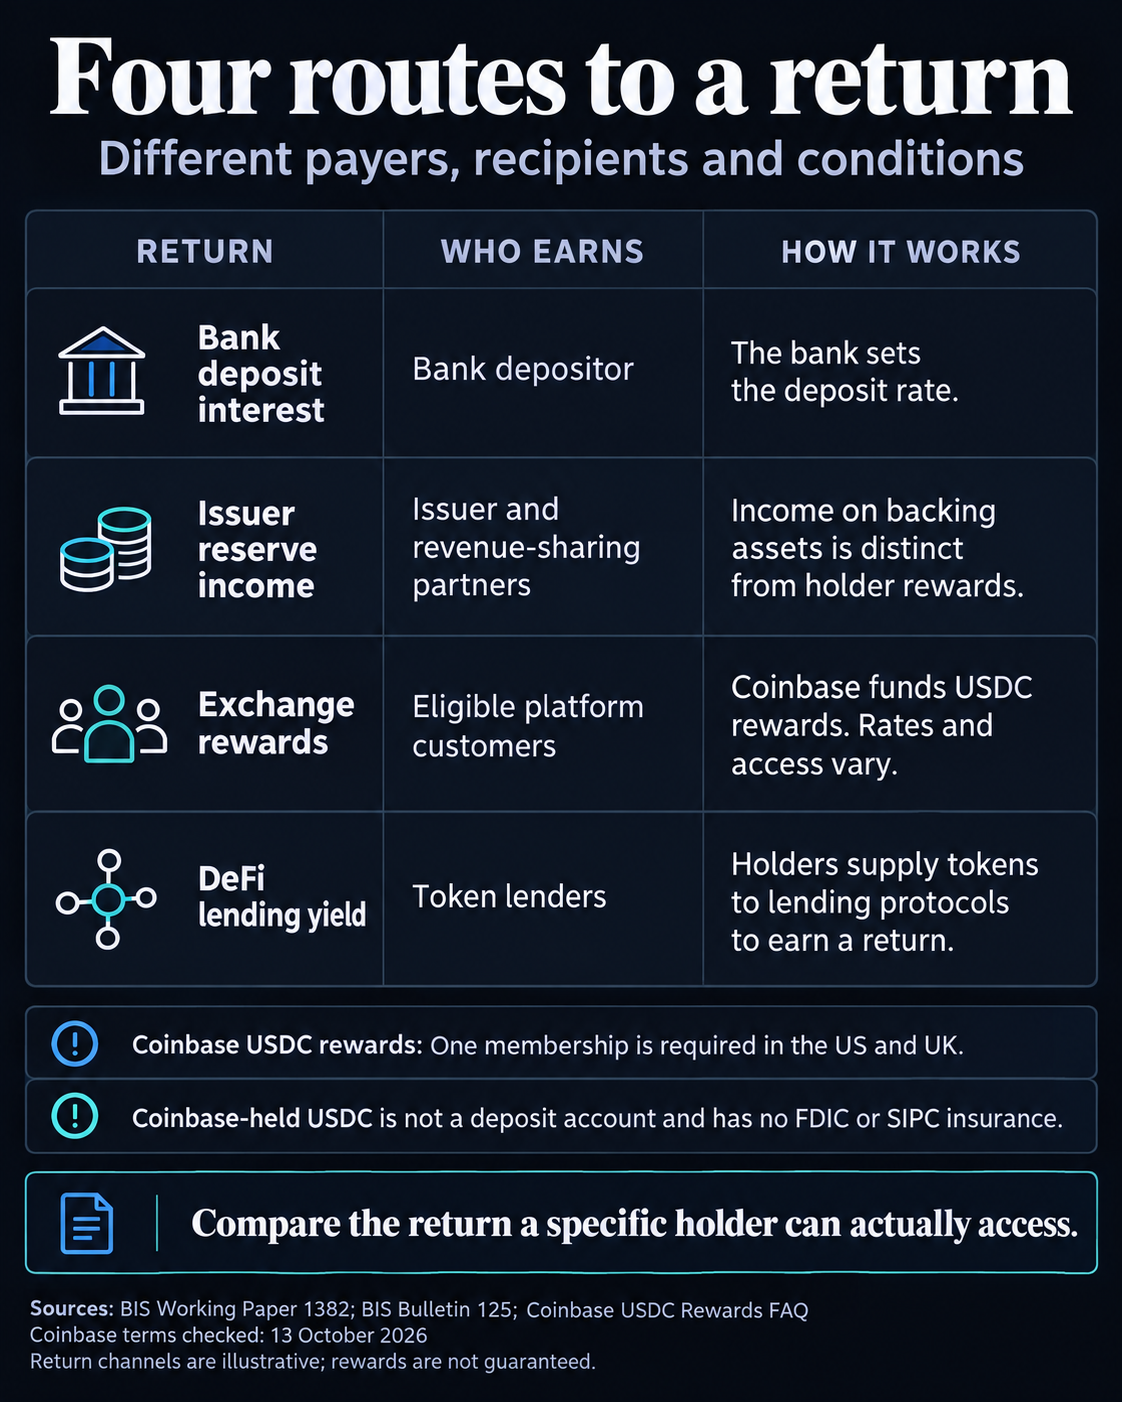
Coinbase’s current rewards terms describe USDC Rewards as a loyalty program funded by the exchange without using or lending a customer’s USDC without instruction.
Coinbase also requires customers to be in an eligible region, be eligible to trade, and hold at least $1 of USDC. Its FAQ also requires Coinbase One membership in several regions, including the US and UK.
Rates vary by country, account type, and ongoing experimentation, and Coinbase can change them or discontinue the program. The public FAQ directs users to account-specific rates and does not establish one current annual percentage yield (APY) available to every USDC holder.
These conditions complicate a bank-account comparison. The relevant return depends on the actual customer and offer, alongside any membership costs and differences in risk. Coinbase says USDC balances in its accounts are not deposit accounts and lack FDIC or SIPC insurance.
Exchange rewards already existed during part of the study’s sample, and the working paper acknowledges third-party yields and includes a DeFi-yield control in its robustness analysis.
That control does not estimate today’s Coinbase membership requirements or every exchange’s account-specific reward spread. Native issuer interest, exchange-funded rewards and yields from lending tokens remain distinct mechanisms.
Demand competition leaves the lending question open
The working paper’s authors explain that stablecoin funds are ultimately reinvested, potentially redistributing deposits across institutions and depositor types depending on the issuer’s counterparties.
Reserve routing and depositor composition could affect bank funding costs. The current demand estimates address a different part of that chain: how stablecoin balances respond to what banks offer depositors.
A larger response for USDC cannot be converted directly into a figure for lost bank lending. That would also require evidence on where reserves go, how banks replace funding and how they adjust credit provision.
The study estimates responses to changes in deposit rates, but its coefficients cannot be applied directly to a Federal Reserve rate move, because bank repricing and the return available on each platform are separate inputs.
A useful forecast would distinguish issuers, the location and preferences of their holders, banks’ repricing, and access to exchange rewards. Updated evidence connecting issuer growth with the actual bank-versus-platform returns available to comparable users would help establish how far the historical relationship extends into the next phase of adoption.

